$25,000 Is All Georgia Requires
The Coverage Gap Nobody Warns You About
Ask me which part of Georgia car accident law puts me up on a soapbox, and this is it. People get annoyed with me when I start in on this one. I keep going anyway, because in over twenty years of practice I have watched this single gap do more damage to more families than any legal technicality I could name.
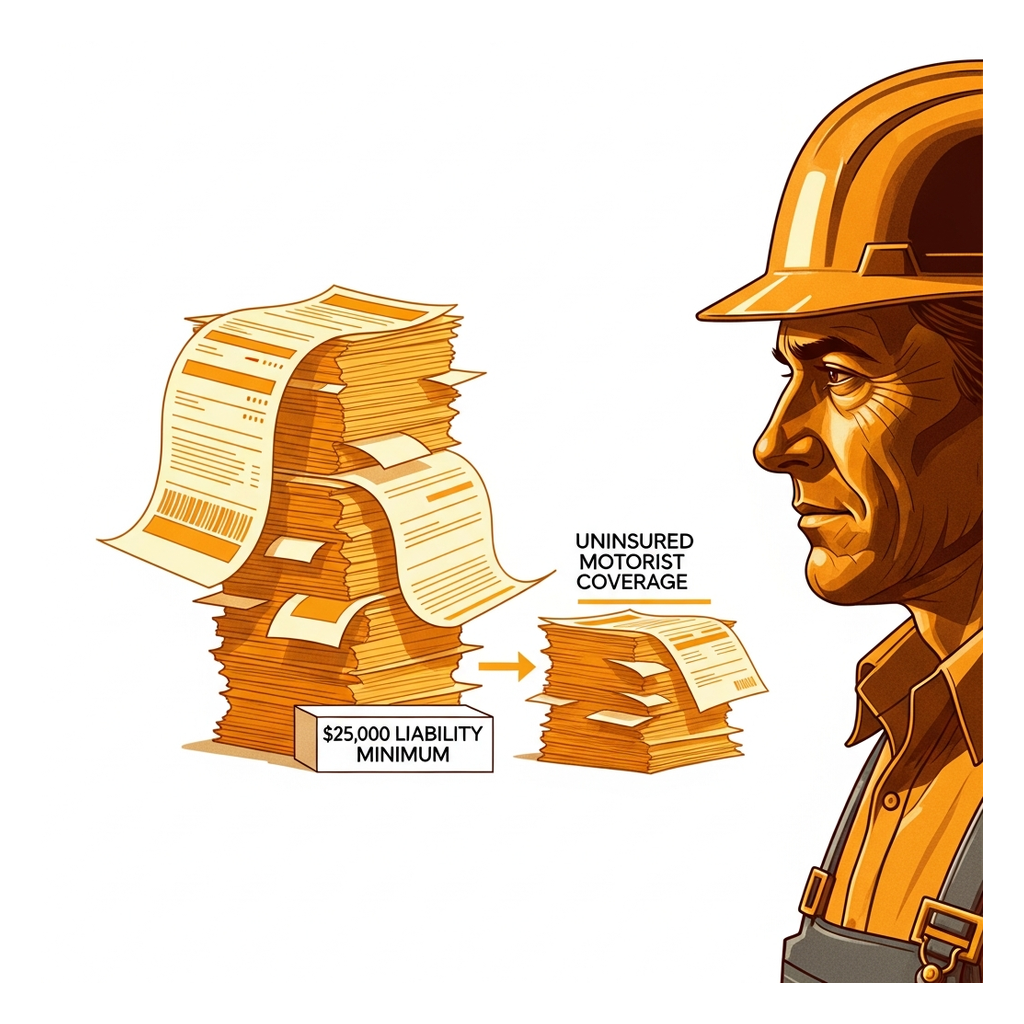
Here is what almost nobody knows until the worst day of their life. Georgia requires a driver to carry $25,000 in liability coverage. That is the whole requirement. Liability coverage is the coverage that pays out when that driver is the one at fault, so it is the money that becomes available to you when they hit you. Past that, the law asks for nothing. No medical payments coverage. No uninsured or underinsured motorist coverage. A driver in Lawrenceville can go an entire lifetime carrying the bare minimum and be legal every mile of it.
Now, $25,000 sounds like a real number right up until you set it beside a hospital bill. I tell people it is like Russian roulette out there. You do not know who is going to hit you, and you have no way of knowing how much coverage that person carries when they pull out in front of you on the way to work.
UM coverage, get as much as you can because it comes into play. You don't have to have it in Georgia, and for some reason, agents oftentimes don't explain this to people. They're all about, 'Oh, protect your assets,' and all of this. When really what they should be pushing is you need as much UM coverage as possible because it comes in, and it's not just when people have no insurance that are at fault, it's also underinsured.
A Number Set in the 1970s, Measured Against Bills From Today
They have not raised that minimum since, I believe, the 1970s. At the time it went to $25,000, that was plenty of coverage. It genuinely was. A serious injury case in that era could resolve inside that number and everyone walked away whole.
Look at what $25,000 buys now. You can barely get out of an emergency room without having ten, fifteen, twenty thousand dollars in medical costs. One ambulance ride, one round of imaging, one night of observation, and a large share of that policy is already spoken for.
And here is the part people misread. That $25,000 is not the medical bucket with more money waiting behind it. It is everything in your entire case. Your medical bills come out of it. Your lost wages come out of it. Your pain and suffering comes out of it. If that is all the at-fault driver has, that is it, and the number does not grow to match how badly you were hurt.
What drives me crazy in my practice is the mismatch. I get cases where the injuries are minimal and a tractor-trailer was at fault, and that trucking company is sitting on a million dollars of coverage the case will never come close to needing. Then I get the horrific ones, the cases where somebody's life changed permanently, and the available coverage is $25,000. Nobody assigns it fairly. It lands where it lands.
The Motorcycle Client on I-85
I had a client who was on a motorcycle on I-85. A car did not see him and swerved into him. He was in the hospital for four months and nearly died.
His medical bills ran somewhere in the range of four to five hundred thousand dollars. The driver who hit him had $25,000 in coverage.
He was a blue-collar worker. He did not have the money. So now there is a bill in the hundreds of thousands sitting against his mortgage, his house, everything he owns, and he has nothing else he can pursue against the other party. That driver had no meaningful personal assets to go after, which is almost always the case. It is all about insurance. When the insurance runs out, the case runs out, no matter how catastrophic the injuries are or how clearly the other driver was at fault.
That is the story I carry into every conversation I have about coverage.
The Line on Your Policy Called UM
So here is the actual advice, and it is the reason this chapter exists at all. Go pull out your auto insurance policy. Look under the line for UM, which stands for uninsured or underinsured motorist coverage.
That is coverage you purchase on your own auto policy. It is there to protect you and your family for this exact scenario. You do not know who is going to hit you, and you do not know how badly you are going to be injured, and UM is the only thing standing between those two unknowns and a bill you cannot pay.
For some reason, agents often do not explain this to people. They are focused on protecting your assets, which is a real concern and not a wrong thing to sell. But it is the wrong emphasis. What they should be pushing is UM, because UM is the coverage that shows up when the person who hit you does not carry enough. It is not only for drivers with no insurance at all. It covers underinsured drivers too, which is the far more common situation on Atlanta roads.
Run the math on my motorcycle client. If he had carried at least $100,000 of the good type of UM, it would have sat right on top of the at-fault driver's $25,000. That is $125,000 of available coverage instead of $25,000. It does not make him whole against four hundred thousand in bills. It is a different life than the one he ended up with.
There are two different types of UM, and I am not going to get too far into the weeds on that here because there is a lot to it. What I tell people is simpler than the weeds. Get as much as you can afford. It is cheap compared to liability, and it is there to protect you and your family.
Common Questions
- Does Georgia require uninsured motorist coverage?
- No. Georgia requires liability coverage only, and the minimum is $25,000. You do not have to carry medical payments coverage and you do not have to carry UM. "You don't have to have it in Georgia, and for some reason, agents oftentimes don't explain this to people." That means the coverage protecting you from an underinsured driver is entirely your decision to buy.
- What happens if the at-fault driver only carries the state minimum and my medical bills are higher?
- You are limited to what is available unless you have UM coverage of your own. The $25,000 covers your entire case, not just the medical side, so pain and suffering and lost wages come out of the same policy. If there is nothing else to pursue, you can be left holding the rest of the bill yourself. That is exactly what happened to my motorcycle client.
- How much UM coverage should I buy?
- Get as much as you can afford. I am not going to hand you a number, because what you can carry depends on your budget and your family. What I will say is that UM is cheap compared to liability coverage, and the amount that feels like plenty on a normal Tuesday is not the amount you will wish you had bought after a four-month hospital stay.
- Why didn't my insurance agent explain UM coverage to me?
- I wish I had a satisfying answer. In my experience, agents lead with protecting your assets, and UM gets mentioned in passing or not at all. It is worth calling your agent directly and asking what your UM limits are and what it would cost to raise them.
Chapter Reflection
Everything else in this book is about protecting a claim after somebody else has already made a decision that changed your day. This chapter is the one thing on the list you can control before anything happens. The at-fault driver's coverage is not up to you. Your own is. Look at the policy. Find the UM line. That five-minute phone call to your agent is the cheapest protection in this entire book, and it is the only one you can still make today. Fault, though, is a separate fight from coverage. Even when the money is there, somebody still has to decide who caused the wreck, and that decision does not happen the way most people assume it does. Ted's full soapbox on Georgia's coverage minimum is worth hearing in the episode this chapter draws from.